How the affordability check works
- Add a contingency. We add your contingency percentage to the project cost, because surprises are normal: the total is what you should be ready to pay.
- Subtract your cash. Whatever's left is the gap you'd need to borrow or save.
- Price the gap as a loan. We use the standard fixed-rate amortization formula: payment = gap × r ÷ (1 − (1 + r)−n), where r is the annual rate ÷ 12 and n is the number of monthly payments. Change the rate and term to match a real offer.
- Compare with your monthly budget. If the payment fits, the verdict is yes. Up to 20% over is “tight”. Beyond that it's “not yet”, and we show how long saving the gap would take instead.
Worked example. A $40,000 project with a 15% contingency comes to $46,000. With $25,000 in cash, the gap is $21,000. Borrowed at 8.5% for 10 years (r = 0.085 ÷ 12, n = 120), that's about $260 a month, so a $400 monthly budget covers it.
How we suggest a contingency Estimate
The suggested percentage comes from the guidance in our remodel contingency guide: it depends on how much of the house you open up, and we add 5 points each for a home 30 or more years old and for known problems like water damage or unpermitted work. The calculator shows the middle of the range; the table shows the full ranges.
| Type of work | Newer home Estimate | Home 30+ years old Estimate |
|---|---|---|
| Cosmetic refresh | 5% – 10% | 10% – 15% |
| Same-layout remodel | 10% – 15% | 15% – 20% |
| Layout change, addition or structural work | 15% – 20% | 20% – 25% |
Estimate Our planning guidance, not a sourced figure. The contingency guide explains the reasoning and the sources behind it.
Ways to close a gap
- Trim the scope. Keeping the layout is usually the biggest single saving in kitchens and baths. Our cost per square foot calculator shows how much each finish level changes the price.
- Phase the work. Do the parts that are hard to redo later (plumbing, electrical, structure) now, and the finishes later.
- Get more bids. Compare at least three itemized bids against the same scope. See how to compare contractor bids.
- Save first. The verdict shows how many months of your monthly budget would cover the gap without borrowing.
- Compare financing carefully. Home equity loans, home equity lines of credit, personal loans and cash-out refinancing have different rates, fees and risks, and borrowing against your home puts it on the line. Compare total cost, not just the monthly payment.
Remodel Budget Starter
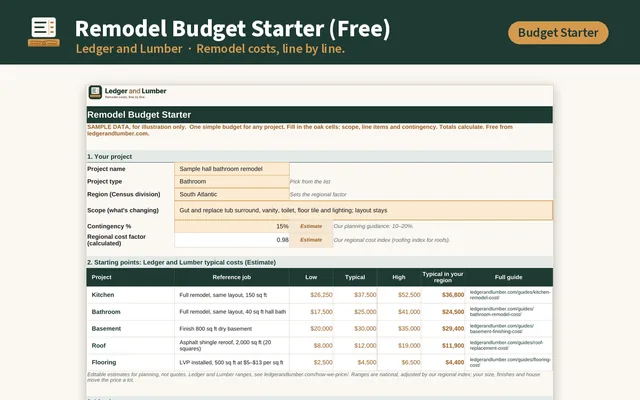
Once the numbers work, put them in a one-page budget with a built-in contingency row. Free, for Excel and Google Sheets.
Get it freeRemodel affordability FAQ
How do I know if I can afford a remodel?
Add a contingency to the project cost, subtract the cash you can put in, and check whether the payment on the remaining gap fits your monthly budget. If you can pay cash including contingency, you can afford it; if the payment fits comfortably, you likely can with financing.
How much contingency should I add?
Our guidance is 10% to 20% for most remodels: around 5% to 10% for cosmetic work, 10% to 15% for a same-layout remodel, and 15% to 20% for layout changes and additions, plus 5 points for an older home or known problems.
What interest rate should I use?
Use a rate a lender has actually quoted you. The default is only an example, and rates vary with the loan type, your credit, the term and the market.
Is the monthly payment exact?
No. It's the standard payment for a fixed-rate loan with no fees. Lines of credit with variable rates, interest-only periods, closing costs and origination fees all change the real figure.
Should I borrow for a remodel?
That's a personal decision, and this calculator isn't financial advice. Many homeowners save for part of the cost and borrow the rest; whatever you choose, keep a contingency and compare offers on total cost.
More free calculators
Estimate Every result on this page is a Ledger and Lumber estimate for planning, not a quote. Ranges are blended from published cost data cited on each cost guide; see How we build our ranges and how we build metro factors. Get itemized local bids before you commit.